
MB-310 · Question #382
Drag and Drop Question A company uses Dynamics 365 Finance. The company adheres to United States Generally Accepted Accounting Principles (US GAAP). You need to create a lease liability amortization…
The correct answer is Right-of-use asset; Operating lease liability. Operating Lease Liability Amortization in D365 Finance (US GAAP / ASC 842) Background Under ASC 842, an operating lease is recognized on the balance sheet with two paired accounts at commencement: A Right-of-Use (ROU) asset (what you control) An Operating lease liability (what…
Question
Exhibit
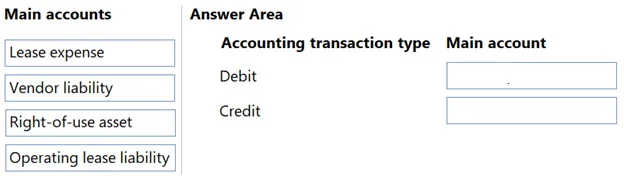
Answer Area
Drag items
Correct arrangement
- Right-of-use asset
- Operating lease liability
Explanation
Operating Lease Liability Amortization in D365 Finance (US GAAP / ASC 842)
Background
Under ASC 842, an operating lease is recognized on the balance sheet with two paired accounts at commencement:
- A Right-of-Use (ROU) asset (what you control)
- An Operating lease liability (what you owe)
Over the lease term, both balances must be systematically reduced. The "lease liability amortization" transaction is the periodic entry that does this.
Why These Two Accounts
The core journal entry for operating lease liability amortization in D365 Finance:
| Role | Account |
|---|---|
| Debit (liability reduced) | Operating lease liability |
| Credit (asset reduced) | Right-of-use asset |
Both accounts were created together at lease inception; they are reduced together through amortization. This is what the drag-and-drop is testing.
Placement-by-Placement Reasoning
1. Right-of-Use Asset The ROU asset is credited (reduced) as the lease "expires" over time. For operating leases, the ROU asset functions as the plug account - it absorbs the difference between the straight-line lease expense and the interest accrual, ensuring straight-line total expense recognition. It belongs in this transaction because it is the asset side of the amortization entry.
2. Operating Lease Liability The lease liability is debited (reduced) as payments are made and the obligation decreases. This is the liability side of the amortization. Amortizing it is what the transaction is literally named for - it must appear here.
Why the Other Options Don't Belong Here
Lease expense - Recognized in a separate periodic entry (Dr. Lease expense / Cr. Accrued liability or cash). It is not part of the liability amortization transaction itself.
Vendor liability - Belongs to accounts payable/procurement workflows. It has no role in lease accounting entries under ASC 842.
Common Mistakes
- Confusing operating vs. finance leases: Finance leases split the expense into interest + amortization, using an interest expense account. Operating leases use straight-line lease expense instead - don't substitute those accounts here.
- Putting lease expense in the amortization entry: The straight-line expense is recorded separately. The amortization transaction only touches the balance sheet accounts (ROU asset + liability).
- Using vendor liability: This is a classic distractor. Lease liability is not a vendor/AP liability - it is a separate long-term obligation class under ASC 842.
Topics
Community Discussion
No community discussion yet for this question.